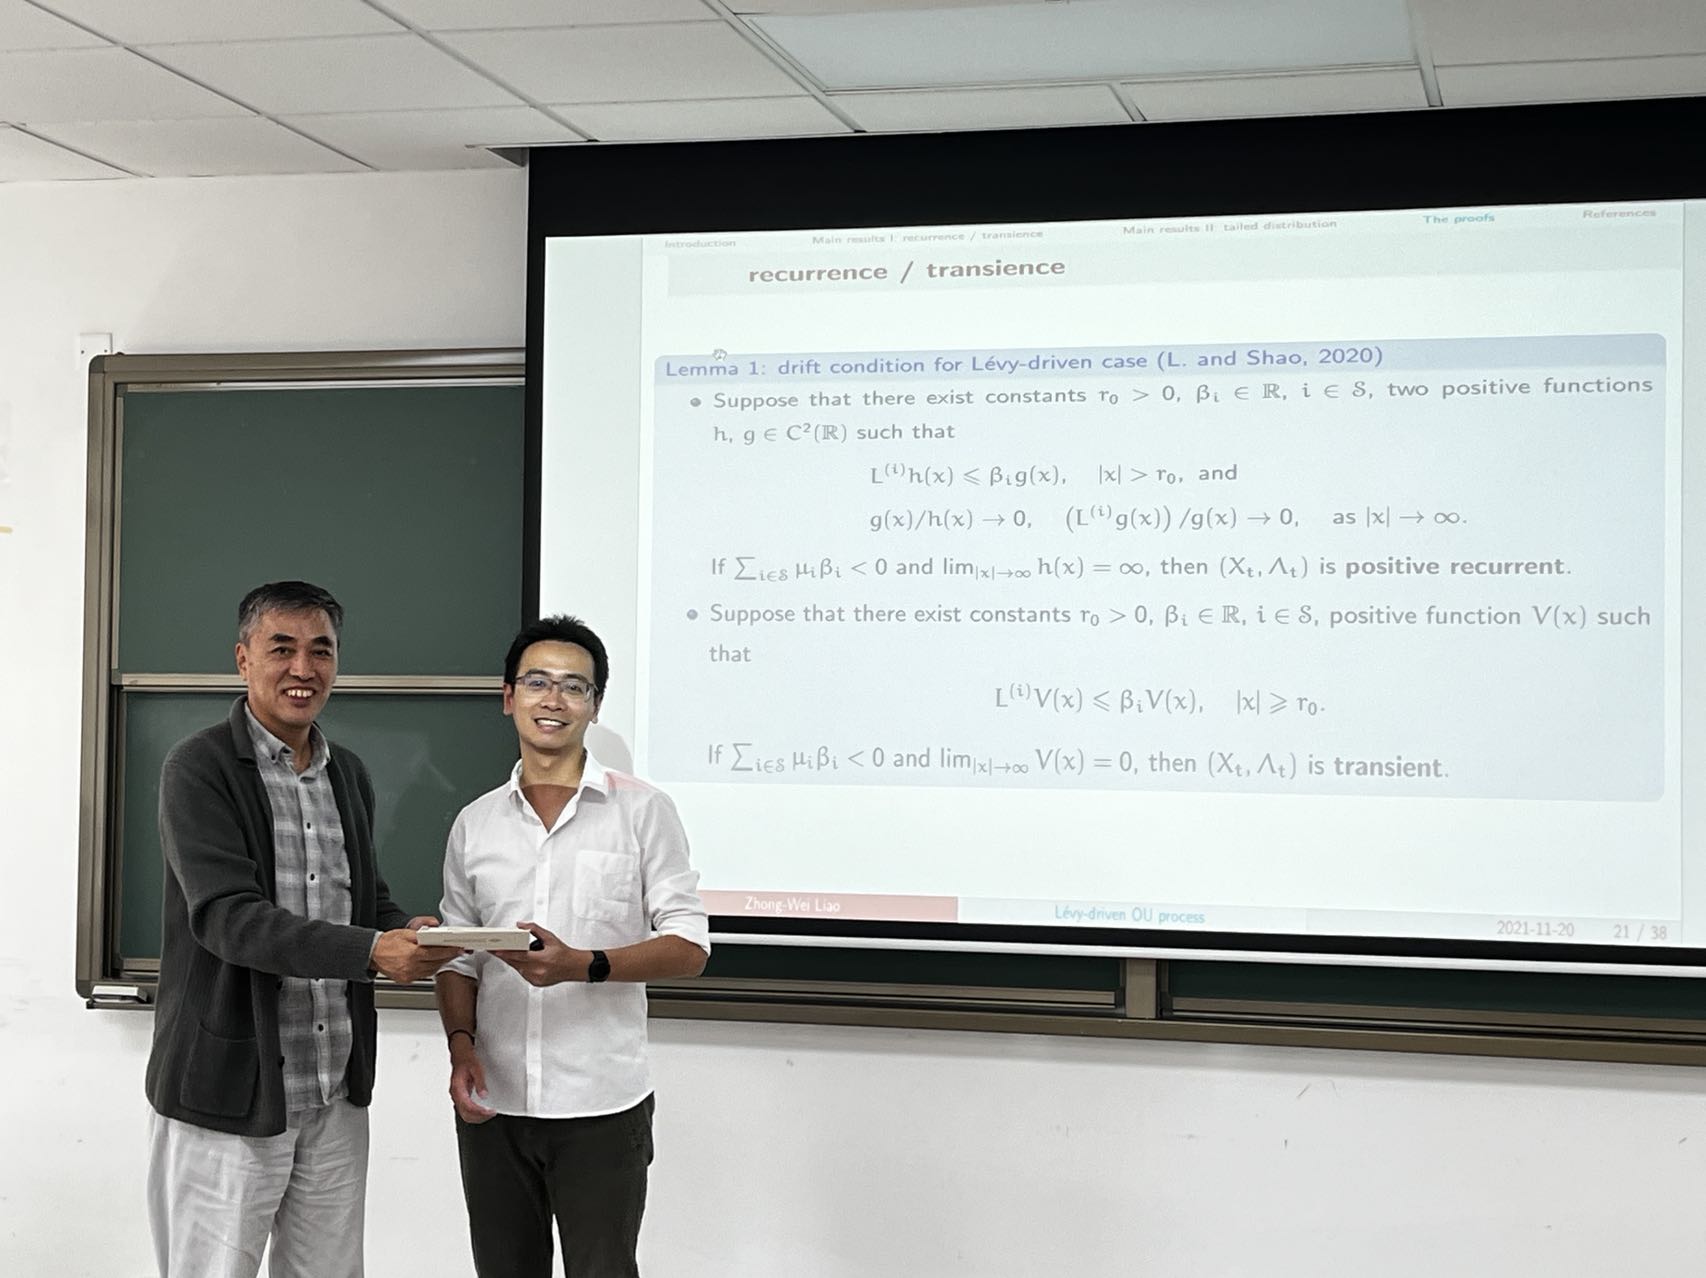

Dr. Zhongwei Liao (廖仲威博士)
北京师范大学
廖仲威,北京师范大学珠海校区。毕业于北京师范大学,先后在中山大学和华南师范大学工作,并于澳大利亚墨尔本大学担任访问学者。现为北京师范大学珠海校区未来教育学院副教授。
Abstract 摘要
In this work we investigate the long-timebehavior of the Ornstein- Uhlenbeck process driven by Levy noise withregime-switching. We provide explicit criteria on the transience and recurrenceof this process. Contrasted with the Ornstein-Uhlenbeck process driven simplyby Brownian motion, whose stationary distribution must be light-tailed, boththe jumps caused by the Levy noise and regime-switching described by Markovchain can derive the heavy-tailed property of the stationary distribution. Inthis work, the different role played by Levy measure and regime- switchingprocess is clearly characterized.
Speaker Biography 讲者简介
廖仲威,北京师范大学珠海校区。毕业于北京师范大学,先后在中山大学和华南师范大学工作,并于澳大利亚墨尔本大学担任访问学者。现为北京师范大学珠海校区未来教育学院副教授。研究兴趣:随机过程稳定性;马氏决策过程与最优化理论;Stein方法等。主持国家及省部级项目多个,研究工作发表于《SIAM J. CONTROL OPTIM.》,《FRONT. MATH. CHINA》,《J. THEORET. PROBAB.》,《J. APPL. PROB.》,《ADV. NONLINEAR STUD.》, 《Acta Math. Sin.》,《STOCH. ANAL. APPL.》等期刊。
Highlights(精彩看点)