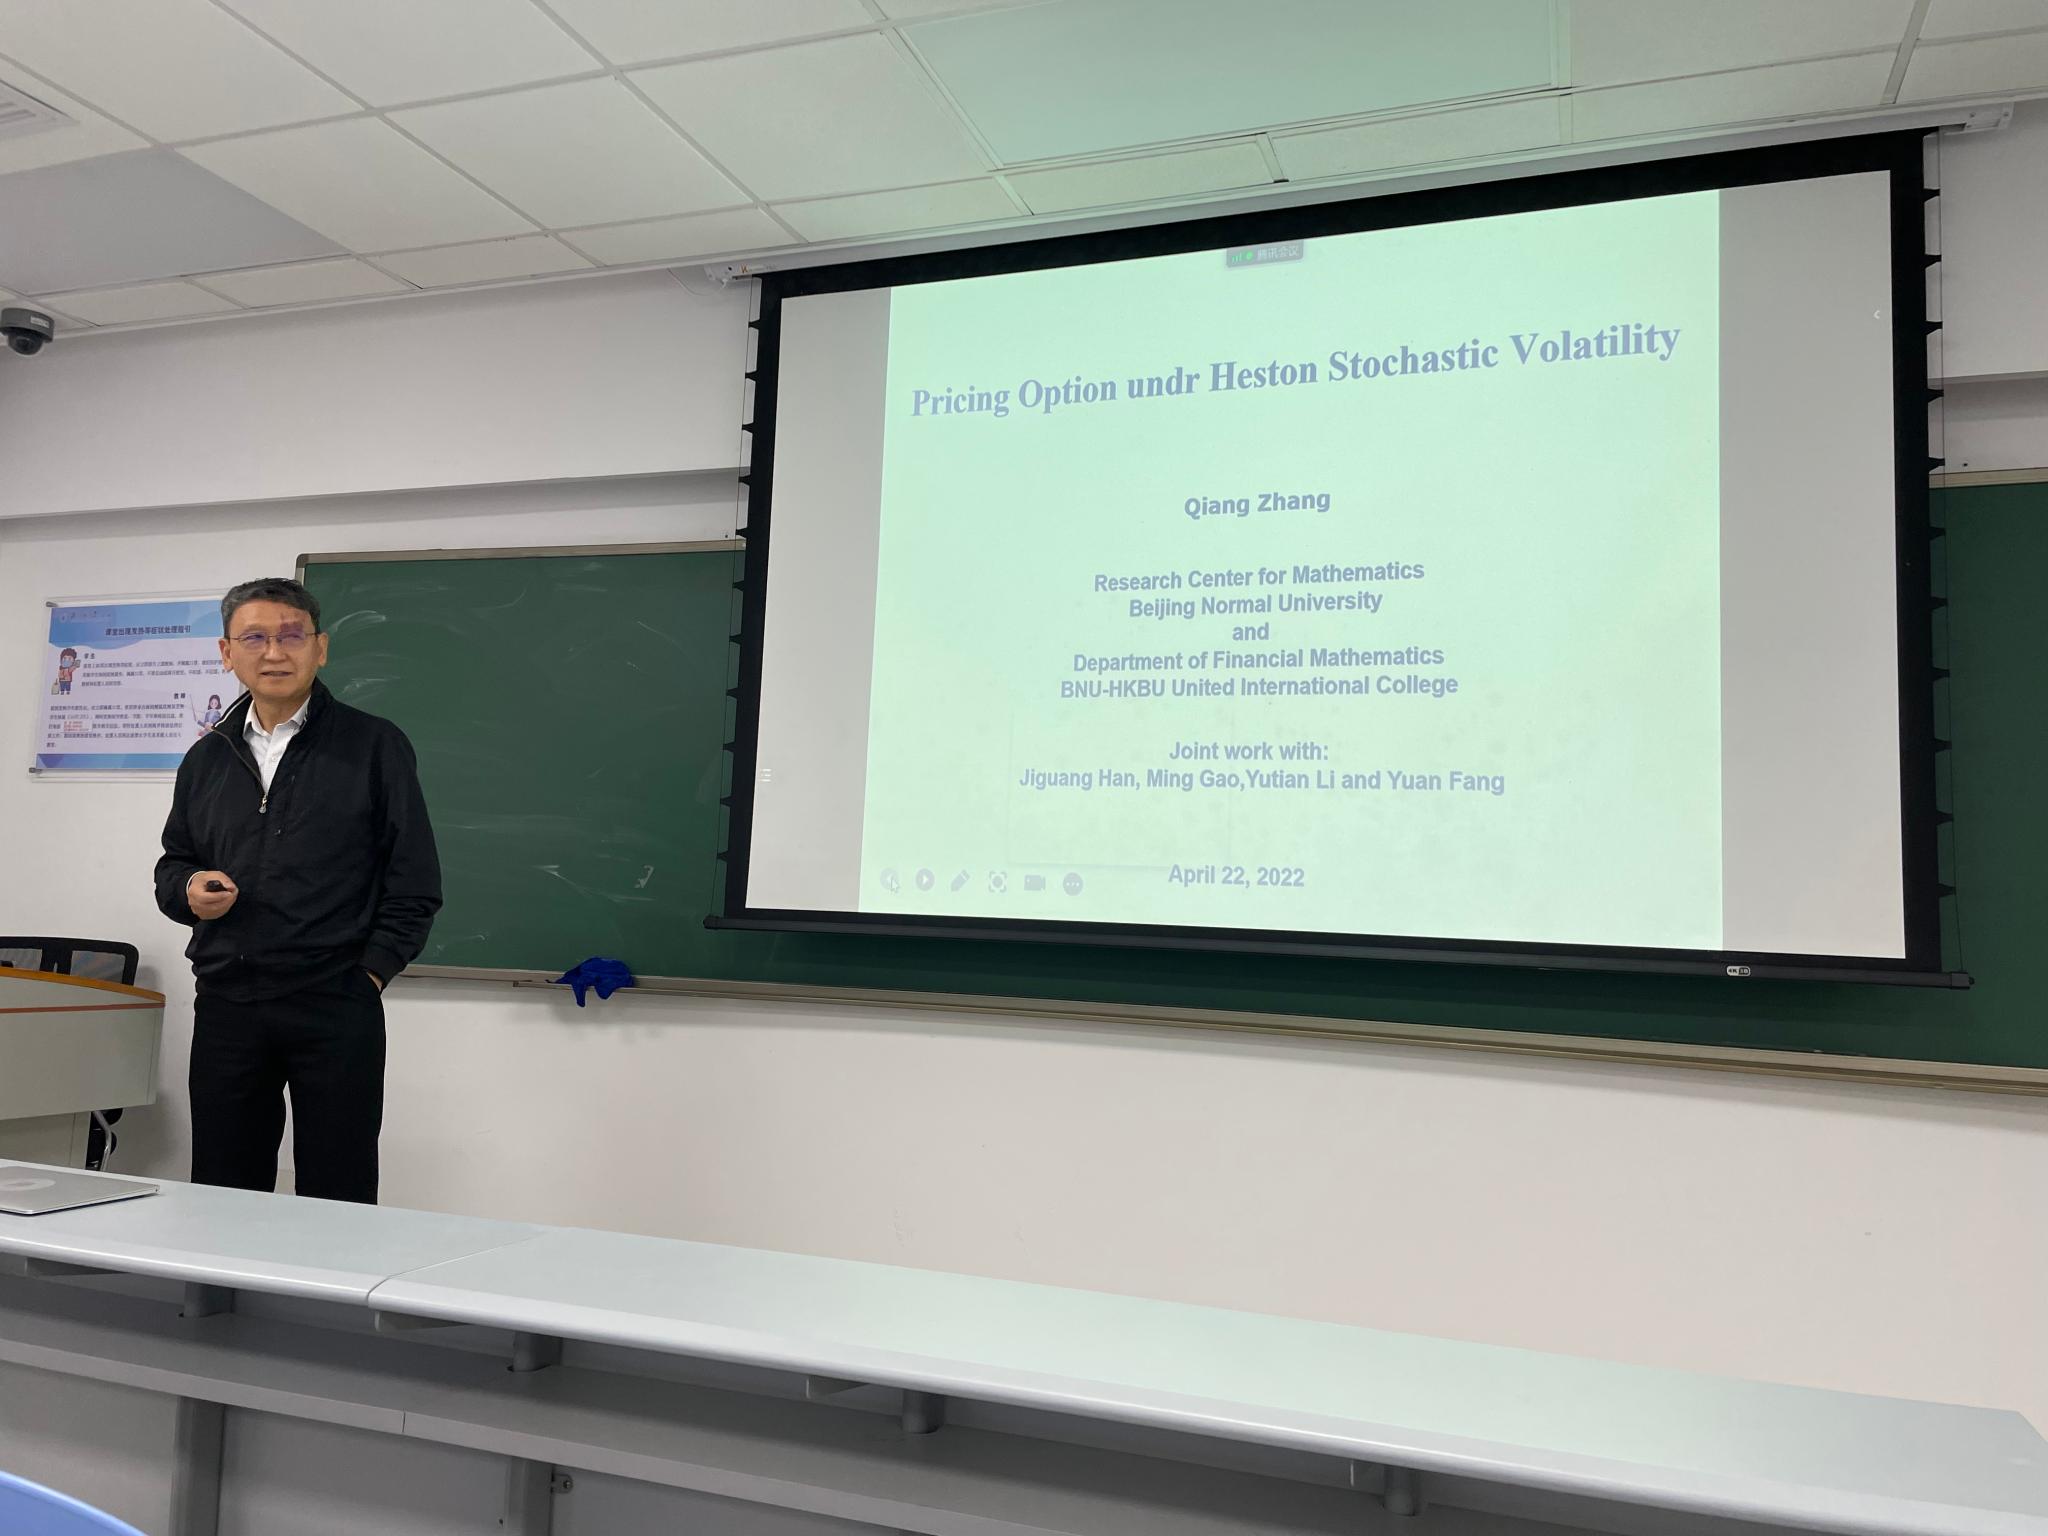

Prof. Qiang Zhang (张强教授)
北京师范大学&北师港浸大
Qiang Zhang is a professor in the Department of Financial Mathematics at BNU-HKBU United International College and a member of Research Center for Mathematics of Beijing Normal University.
Abstract 摘要
The well-known Heston model for stochastic volatility captures the reality of the movement of stock prices in our financial market. However, the solutions for option prices under the stochastic volatility model are expressed in terms of integrals in the complex plane. There are difficulties in evaluating these expressions numerically. We present closed-form solutions for option prices and implied volatility under Heston model of stochastic volatility. We method is based on a multiple-scale analysis in singular perturbation theory. Our theoretical predictions are in excellent agreement with numerical solutions of the Heston model of stochastic volatility. We also show that our approximate solution is valid not only in the fast-mean-reverting regime, but also in the slow mean-reverting regime. This means that the solutions in these two different regions can be approximated by the same function. We further apply our new approach of multiple-scale analysis to pricing Asian options with stochastic volatility. The results are also in excellent agreement with the exact numerical solutions.
Speaker Biography 讲者简介
Qiang Zhang is a professor in the Department of Financial Mathematics at BNU-HKBU United International College and a member of Research Center for Mathematics of Beijing Normal University. He received B.S. from Fudan University, M.A. and Ph.D. from New York University. After graduation, Professor Zhang worked at the Courant Institute of Mathematics at New York University, the State University of New York at Stony Brook and the City University of Hong Kong. His research spans a wide range of fields, including mathematical finance, fluid dynamics, scientific computing, granular material and physics.
Highlights(精彩看点)